Ecuador’s New EVs Hit Nearly 20% of August Car Sales
Affordable models, tax relief, and higher fuel prices lifted Ecuador’s battery and plug-in hybrid share to 19.3% of new vehicles sold in August 2026, according to CleanTechnica and ZEMO data.
Today’s Progress
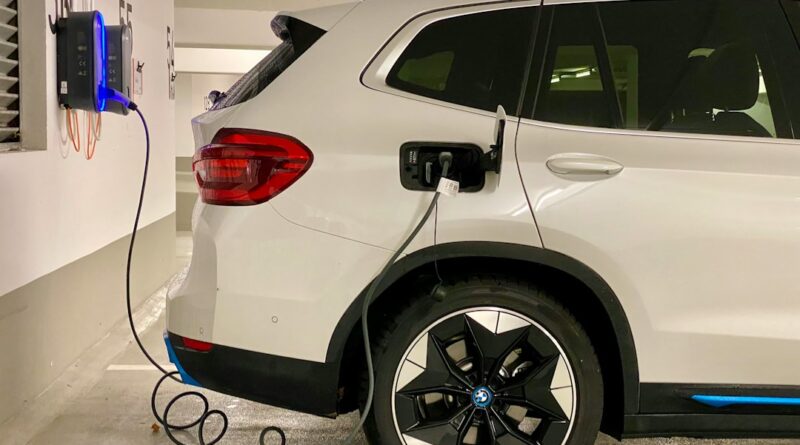
In August 2026, electric vehicles accounted for 19.3% of all new cars sold in Ecuador—13.8% battery-electric (BEV) and 5.5% plug-in hybrid (PHEV)—CleanTechnica reported on 1 October, drawing on figures compiled by ZEMO with input from the national industry association AEADE.
Monthly EV volume approached 3,000 units, with BEVs clearing 2,000 and PHEVs more than 800 for the first time. Year-to-date EV sales were up 276%; August alone was up 426% from a year earlier. Only three years earlier the country sat near the bottom of Latin America’s EV rankings with a handful of sales; earlier reporting showed share had surpassed 2% and was hovering around 3%.
The mix is still BEV-led (roughly 70/30 with PHEVs). BYD remains the volume leader but its share has fallen from above 70% in 2024 to under 30% in 2026 as competition widened. Chevrolet (rebranded Chinese models) and Kia—lifted by the Slovakia-built EV2—followed in August. Popular models included the BYD Yuan Up and Seagull, the Chevrolet Spark EUV, the DFSK E5 plug-in SUV, and the newly arrived Chery iCar V23, a compact electric off-roader priced near established 4×4 ICE rivals.
CleanTechnica links the surge to tariff and tax exemptions that lower sticker prices and to the government’s earlier end of gasoline and diesel subsidies, which raised fuel costs and improved the relative economics of plug-in cars. The same period has seen a broader post-pandemic boom in total vehicle sales, so combustion models are still growing in absolute terms; EVs have not yet reversed ICE growth the way they have in markets such as Uruguay.
Why This Matters
Every additional electric mile displaces gasoline or diesel combustion in a country long dependent on imported refined fuels. Higher EV share therefore cuts tailpipe emissions in cities and towns and reduces exposure to volatile fuel prices for households that can switch. Capable, relatively affordable models suited to Andean rural roads—such as the iCar V23—could extend that option beyond dense urban early adopters.
The benefit is still partial. Total car sales remain strong, so absolute fossil-fuel vehicle numbers have not yet peaked. Sustained climate and air-quality gains will depend on whether EV growth continues to outpace ICE growth and on the carbon intensity of the electricity that charges the fleet.
Evidence and Context
The August 19.3% figure and the brand/model breakdowns are monthly sales tallies reported by CleanTechnica from ZEMO/AEADE data, not a one-off survey or manufacturer claim. Earlier CleanTechnica Latin America updates already showed Ecuador crossing 6% BEV in Q1 2026 and more than 11% combined EV share in Q2, so the August reading continues a documented climb rather than an isolated spike.
Limits are clear. One strong month does not guarantee the same share for the full year. ICE volumes are at multi-year highs, so net fleet decarbonization is slower than the EV percentage alone suggests. Charging-network coverage, rural grid reliability, and long-term battery and electricity costs are not quantified in the sales report. PHEV real-world electric miles also vary with driver behavior.
What Made This Possible
Policy and product timing aligned. Ending retail fuel subsidies raised operating costs for ICE vehicles just as Chinese and other makers shipped smaller, cheaper BEVs and PHEVs into the market under tariff and tax relief. CleanTechnica links that combination to improved relative economics that helped volume models compete with conventional crossovers. A more open competitive field—BYD no longer holding over 70% of sales—further expanded choice and price pressure.
Progress Toward Global Goals
Faster uptake of zero- and low-tailpipe-emission cars can support SDG 13 (Climate Action) by potentially cutting transport greenhouse-gas emissions per kilometer driven, and SDG 11 (Sustainable Cities and Communities) where urban air quality may improve as the EV share of the circulating fleet rises. Alignment is outcome-based on sales and displacement potential, not on branding. No SDG is clearly undermined by the shift itself; unresolved questions remain about electricity supply and the full vehicle lifecycle.
Building on This Success
The following possibilities were generated with the assistance of AI to explore how this progress might be improved, expanded, or adapted. They are ideas for further investigation, not established findings or recommendations from the people featured in the original reporting.
If ministries and utilities paired the existing tax treatment with targeted public and workplace charging along major Andean corridors, rural and intercity buyers of models like the iCar V23 might keep a higher share of miles electric; a measurable test would be public-charger utilization and average kWh delivered per registered EV outside Quito and Guayaquil within 12–18 months. Local governments could also trial preferential parking or low-emission zones that reward verified BEV/PHEV registrations, with success judged by the change in ICE share of peak-hour city traffic. Fleet operators of buses and light trucks—already sensitive to diesel price swings—might pilot depot charging if concessional finance lowered upfront cost; the test would be diesel liters avoided per vehicle-year against a matched ICE control group.
What policy and market shifts pushed Ecuador’s electric vehicles to nearly one-fifth of new car sales in August 2026?
Tariff and tax exemptions that lowered EV purchase prices, the end of gasoline and diesel subsidies that raised ICE running costs, and a rapid influx of affordable BEV and PHEV models from multiple brands—especially Chinese makers and newly competitive European-built options—combined to lift combined EV market share to 19.3% in a single month, per ZEMO-based reporting.
Three Promising Next Steps
- Publish monthly open EV and charger statistics — transport and energy agencies could release standardized BEV/PHEV registrations and public-charger counts so researchers and buyers can track whether the August level holds; success metric: continuous public series within six months.
- Align electricity tariffs for off-peak home charging — regulators might trial time-of-use rates that make overnight charging cheaper than gasoline on a per-kilometer basis; success metric: share of residential EV load in off-peak windows.
- Support rural-ready EV service networks — dealer and independent workshops in highland provinces could receive training and parts logistics for popular off-road EVs; success metric: mean repair turnaround time versus urban benchmarks.
What Readers Can Watch
- Whether September–December 2026 EV share stays near or above the August 19% level in subsequent ZEMO/CleanTechnica updates.
- Absolute ICE sales: does the combustion total finally plateau or fall while EVs keep rising?
- Build-out of public charging outside the largest cities and any change in electricity-mix carbon intensity used for transport reporting.